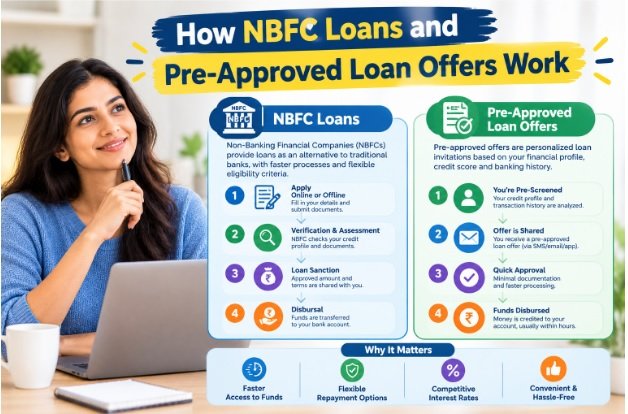
Borrowers today can access credit through banks as well as non-banking financial companies. NBFCs provide several types of financial products and may offer personal loans based on income, credit history and other eligibility factors. Understanding how these loans work can help borrowers compare offers more effectively.
What Is an NBFC Loan?
It is financing provided by a non-banking financial company. NBFCs offer various products, including personal loans and business-related credit, depending on their product portfolio.
Like other forms of borrowing, eligibility and pricing depend on the applicant’s financial profile and the lender’s internal credit policies.
When comparing an NBFC loan, borrowers should examine the interest rate, processing fee, repayment period, eligibility requirements and other applicable charges.
How Does a Pre-Approved Loan Work?
A pre approved loan is an offer made to an existing or prospective customer based on information available to the lender or marketplace. Such offers may be generated using factors such as previous relationship, income details, credit profile or other eligibility information.
However, a pre approved loan offer should not automatically be treated as final approval. The lender may still require verification, documentation and other checks before disbursal.
Benefits of Comparing Different Offers
Different lenders can have different eligibility criteria and pricing structures. Therefore, comparing an NBFC loan with other available options can help a borrower understand the available choices.
Bajaj Markets provides access to multiple personal loan offers and allows borrowers to compare lenders, loan amounts, interest rates and tenure options online.
This can be particularly useful when an applicant receives a pre approved loan offer but wants to know whether another option may provide more suitable terms.
Check the Interest Rate
Interest is one of the most important components of borrowing cost. However, the lowest advertised rate may not always result in the lowest total repayment.
Before selecting an NBFC loan, check whether the rate is fixed or subject to specific conditions. Also calculate the EMI and total interest payable over the selected tenure.
Review Processing and Other Charges
A borrower should examine all fees before accepting a pre approved loan. These can include processing fees, late-payment charges and other costs specified in the loan agreement.
Bajaj Markets’ current personal loan listings show that processing charges can vary between lenders. Therefore, borrowers should review the complete offer instead of comparing only interest rates.
Check Eligibility and Documentation
Eligibility can differ between lenders. Common factors may include age, income, employment status, credit history and existing financial obligations.
Before applying for an NBFC loan, keep identity, address and income-related documents ready. Digital applications can reduce paperwork, but verification is still required.
Understand the Repayment Tenure
A longer tenure may lower the monthly EMI but can increase the total interest payable. A shorter tenure may require a higher EMI but can reduce the repayment period.
If you receive a pre approved loan, compare the EMI at different tenure levels before accepting the offer.
Use Pre-Approved Offers Responsibly
Pre-approved offers can make borrowing more convenient, but borrowers should not accept them simply because they are readily available. Consider whether the loan is genuinely required and whether the EMI fits within the monthly budget.
Final Thoughts
It can provide an alternative source of financing, while a pre approved loan can simplify the initial borrowing process. However, both should be evaluated on affordability, interest rate, fees, tenure and repayment capacity.
Bajaj Markets enables borrowers to compare personal loan options from multiple lenders, helping them review different offers before proceeding.